Landlord Insurance for Long Island & New York

One call to our Melville office compares more than 30 carriers for your building, your liability and your rental income.

Call 516-799-9001

4.9 on Google from 400 reviews

Landlord insurance516-799-9001Get a Quote
This field is for validation purposes and should be left unchanged.
Get my landlord insurance quote
Leave your name and number. A licensed PRK agent in Melville will call you back with landlord insurance quotes. No obligation.

Requesting a quote does not bind coverage.

What is landlord insurance?

It covers a home or building you own and rent to someone else. The building, your liability as the owner and the rent you depend on. A homeowners policy is written for a home you live in, so once a tenant moves in, the policy should change too.

Written for single family rentals, two to four family homes, condos and co ops, small apartment and mixed use buildings, and rentals held in an LLC or trust.

Live in one unit and rent the other? An owner occupied two family home can often stay on a homeowners policy. Tell us how the property is used and we will place it on the right form.

What does landlord insurance cover?

Six parts make up most landlord policies. We check each one against your building before you buy.

The building

Repairs or rebuilds the rental after a covered loss such as fire, wind, lightning or a burst pipe.

Loss of rents

Replaces the rent you would have collected while a unit is unlivable after a covered loss.

Liability

Your legal defense and covered settlements if a tenant or visitor is hurt and you are held responsible.

Other structures

Detached garages, sheds and fences, under their own limit.

Your property at the rental

Appliances, furnishings and equipment you own and keep there. Not your tenant's belongings.

Options worth asking about

Water and sewer backup, equipment breakdown, building code upgrades after a loss, and extra liability through an umbrella policy.

How does loss of rents coverage work?

Rental income is the reason most owners hold the property, and the mortgage, taxes and insurance still come due after a fire. Loss of rents, also called fair rental value, pays the rent you lose while a unit cannot be lived in because of a covered loss.

It usually runs for the time it reasonably takes to repair the damage, up to a dollar limit or a set number of months. When we quote, we check that the limit matches what the property really earns in a year.

How much liability coverage does a landlord need?

Landlord policies are commonly written with $300,000, $500,000 or $1 million of liability. The right limit depends on what you own and what you could lose in a lawsuit. Owners with more than one property, a pool or significant savings often add an umbrella policy, which sits on top of the landlord policy and adds $1 million or more.

Two small steps help as well. Ask each tenant to carry renters insurance, and ask us about adding your property manager to the policy if you use one.

What does it not cover?

Five gaps to know about before a claim, not after.

  • Your tenant's belongings

    They need a renters policy of their own.

  • Flood

    Rising water takes a separate flood policy. Our Long Island flood guide explains the options.

  • Wear and tear

    Maintenance, aging and gradual leaks are the owner's cost.

  • Unpaid rent

    Loss of rents responds to a covered loss, not to a tenant who stops paying.

  • Long vacancies

    Many policies cut back coverage after 30 to 60 days empty. Tell us before a unit sits vacant.

What affects the cost on Long Island?

Each carrier weighs these differently, so the same building can price very differently from one company to the next. Comparing them is what we do.

  • Location

    Distance to the water affects the wind and hurricane deductible, which is often a percentage of the building limit. See coastal home insurance.

  • The building

    Age, construction, roof, wiring, plumbing and heating. Updates can lower the price.

  • How it is rented

    A year lease to a family is priced differently from student housing, seasonal rentals or short term stays.

  • Coverage choices

    The building limit, the liability limit, the deductible and whether claims are paid at replacement cost.

  • Claims history

    Prior losses on the property or with the owner.

What should I ask before buying a landlord policy?

We go through each of these with you before anything is bound.

  • Is the building covered for replacement cost or actual cash value?
  • Is it a named perils policy or an open perils (special form) policy?
  • What is the wind or hurricane deductible, in dollars?
  • How long can a unit sit vacant before coverage changes?
  • Is the owner on the deed, whether that is you, an LLC or a trust, the name on the policy?
  • If the building heats with oil, how would a tank leak be handled?

How does a quote work?

  1. Send your name and number

    It takes about 30 seconds.

  2. A licensed PRK agent calls you back

    During office hours, Monday to Friday, 9 a.m. to 5 p.m. Eastern.

  3. We compare carriers for your rental

    We explain the coverage behind the price. Nothing is bound until you decide.

What do clients say about PRK?

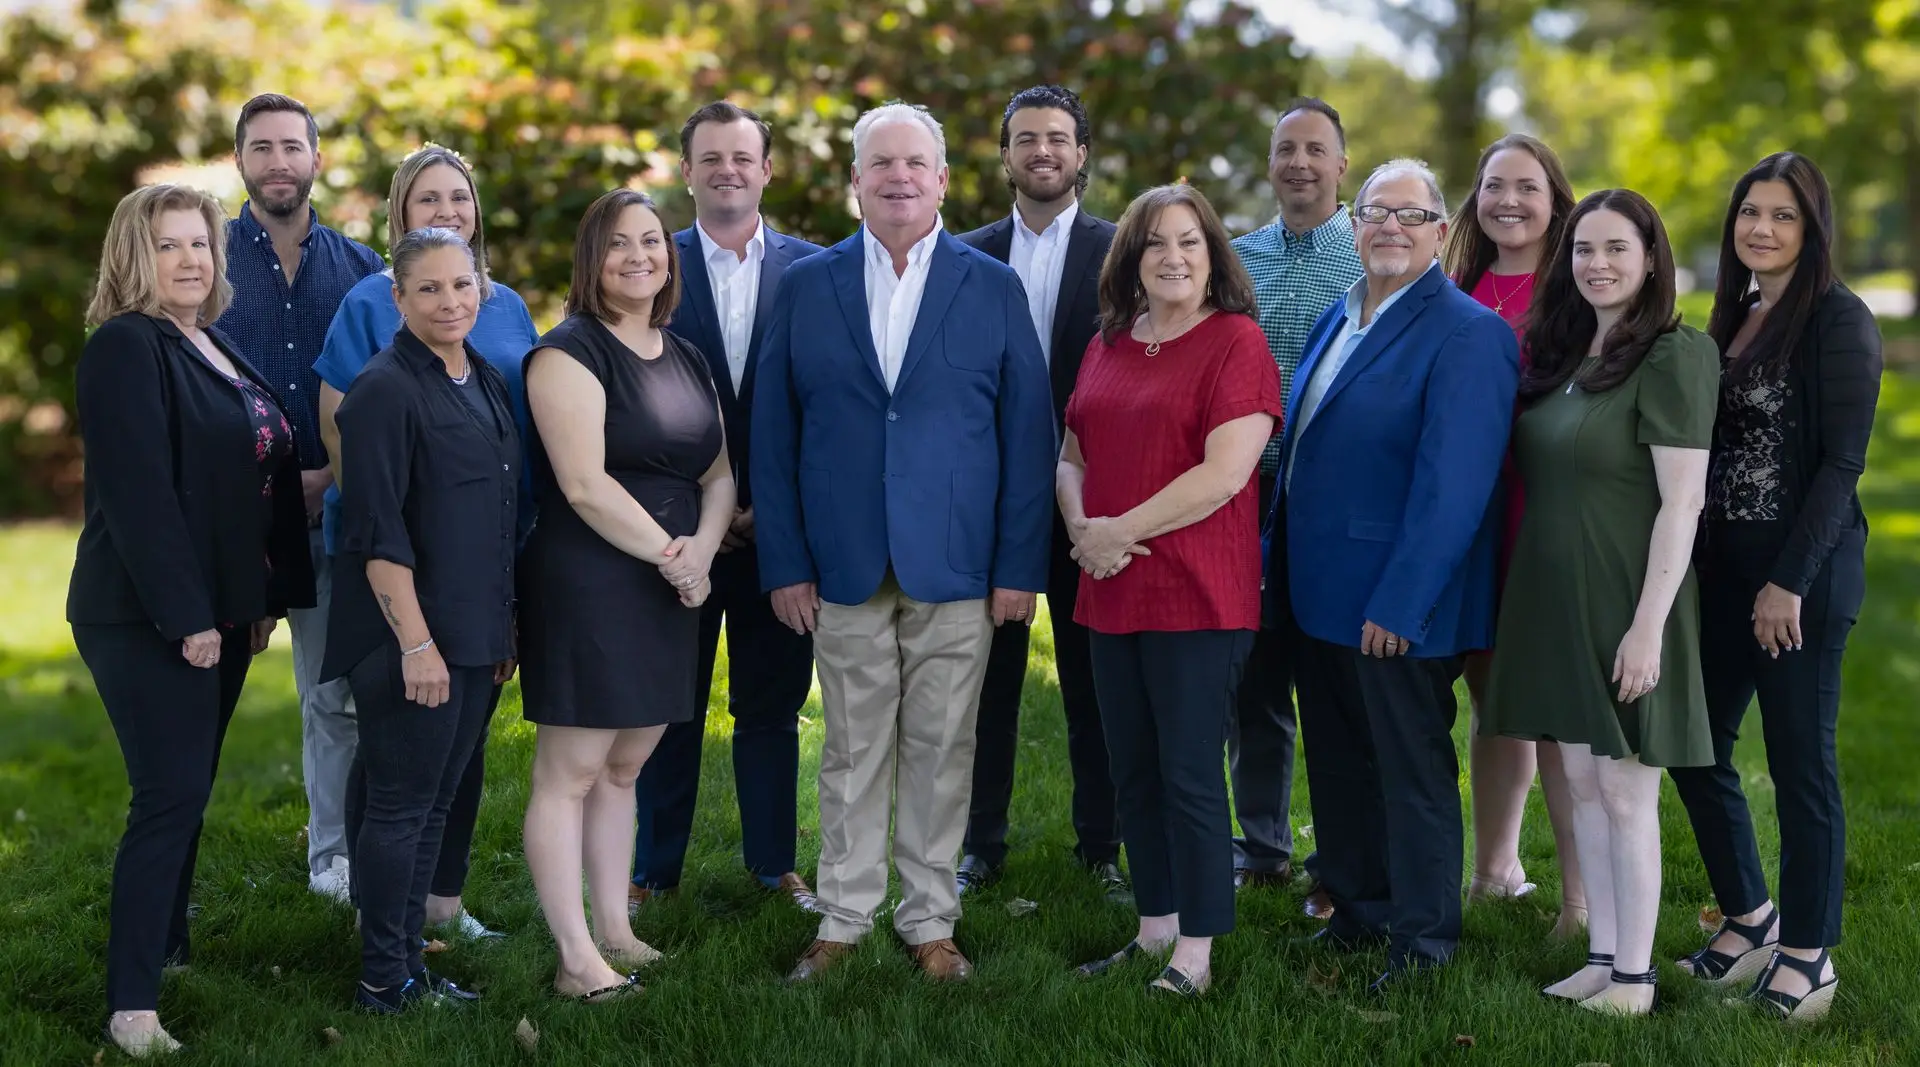
The PRK Insurance Agency team in Melville, New York

Why do landlords choose PRK?

Rental properties come with their own risks, and the right coverage matters. Since 2004, our team in Melville has helped New York property owners compare coverage, avoid gaps and choose policies that fit the building and the way it is rented.

Meet the PRK team or see the companies we represent.

Ready to compare landlord insurance?

Send your number and a licensed PRK agent will call you back, or call the Melville office now.

Long Island guides from our Melville office

Written for homeowners, drivers and business owners across Nassau and Suffolk County.

Get a QuoteRead our Google reviews

Landlord Insurance FAQs

What does landlord insurance cover?

Landlord insurance may cover the rental dwelling, other structures, landlord-owned appliances or furnishings, premises liability, and lost rental income after a covered property loss. Coverage varies for one-to-four-family homes, larger buildings, mixed use, and short-term rentals.

Why is landlord insurance different from homeowners insurance?

Homeowners insurance is primarily designed for an owner-occupied residence. A tenant-occupied property creates different liability, occupancy, rental-income, and property exposures, so using the correct landlord or dwelling policy is important.

Does landlord insurance cover a tenant’s belongings?

No. The landlord’s policy generally protects the building and the landlord’s covered interests, not the tenant’s furniture, clothing, electronics, or personal liability. Requiring renters insurance can help tenants protect themselves and document separate coverage.

Does landlord insurance cover tenant damage?

Damage caused by a covered event may be insured, but ordinary wear, poor maintenance, intentional damage, and certain theft or vandalism losses may be limited or excluded. Security deposits and tenant screening address different risks than insurance.

What does loss-of-rental-income coverage pay for?

It may replace qualifying rental income and certain continuing expenses when covered physical damage makes the property uninhabitable during repairs. It generally does not cover ordinary vacancy, eviction, lease disputes, or a tenant’s failure to pay rent.

Can vacant homes and short-term rentals be insured?

Yes, but vacancy, renovation, seasonal use, and short-term rental activity often require specialized coverage or endorsements. Disclose the actual occupancy, lease length, property management, and platform use so the policy is not based on an incorrect risk description.